Cash-Out Refinance on Investment Property — What California Investors Need to Know


You already own the asset.
The equity is sitting there.
But your capital is locked up — and there's another deal on the table.
That's exactly the scenario cash-out refinancing was built for.
Here's everything you need to know about pulling equity out of an investment property in California.
What Is a Cash-Out Refinance on an Investment Property in California?
A cash-out refinance replaces your existing loan with a new, larger one.
The difference between what you owe and the new loan amount gets paid to you in cash at closing.
Simple example:
Property value: $800,000
Current mortgage: $300,000
New loan at 70% LTV: $560,000
Cash out at closing: $260,000
That $260,000 goes directly to you. No restrictions on how you use it.
Why Investors Pull Cash Out
This is one of the most powerful wealth-building moves in real estate.
Fund the next acquisition — instead of waiting to save up a down payment, you use the equity you already built to fund your next deal. Your money keeps working.
Cover renovation costs — pull equity from a stabilized property to fund a rehab on another one. No need to deplete reserves or take on additional high-cost financing.
Consolidate or pay off debt — replace high-interest hard money or bridge loans with longer-term, lower-cost financing.
Build reserves — liquidity matters. Having cash available means you can move fast when the right deal appears.
Portfolio strategy — some investors cash out on fully paid-off properties to redeploy capital into additional income-producing assets. Let the equity earn more equity.
The Problem With Banks and Investment Property Cash-Out
This is where most investors hit a wall.
Conventional lenders — banks, credit unions, Fannie Mae backed lenders — have strict rules for investment property cash-out refinances:
Maximum LTV typically capped at 75% — sometimes lower
Require 2 years of tax returns showing rental income
Count all existing mortgage payments in your DTI
May require 6 to 12 months of seasoning before allowing a cash-out
Cap the number of financed properties you can have
Won't touch anything that doesn't look like a clean, stabilized long-term rental
If you're self-employed, have multiple properties, or your income looks unconventional on paper — the bank almost always says no.
Private Lending Cash-Out — How It Works Differently
Private lenders underwrite cash-out refinances on investment properties based on the asset — not your tax returns.
Here's what actually matters:
The property value — we order an appraisal or BPO. The loan is based on what the property is actually worth today.
The equity position — how much cushion exists between the loan amount and the property value. We typically lend up to 65–75% LTV on cash-out refinances.
The exit strategy — what's your plan? Are you holding the property long-term, selling, or rolling into permanent financing? We need to understand how the loan gets repaid.
The property performance — if it's a rental, is it occupied? Is it generating income? For DSCR-based cash-out, the rent needs to support the new payment.
What we don't need:
W-2 or pay stubs
2 years of tax returns
Employment verification
DTI calculations based on your personal income
Cash-Out Options for California Investment Properties
Hard Money Cash-Out
Best for: investors who need speed, have lower LTV needs, or own distressed or non-standard properties.
Up to 65–70% LTV
Close in approximately 10 days
1 to 5 year terms, interest only
No income verification
No prepayment penalty
All property types
Bridge Loan Cash-Out
Best for: stabilized properties where you need higher LTV and competitive short-term rates.
Up to 75–80% LTV
Close in 5 to 10 business days
6 to 24 month terms, interest only
No income verification
No prepayment penalty
Minimum 680 credit score
DSCR Cash-Out Refinance
Best for: investors who want long-term permanent financing and qualify on the property's rental income.
Up to 80% LTV
30-year terms available
Qualify based on property cash flow — not personal income
No tax returns required
Minimum 0.75 DSCR
Best for stabilized long-term rentals
Close in 2 to 3 weeks
Bank Statement Cash-Out
Best for: self-employed investors who can't qualify on tax returns but have strong actual cash flow.
Up to 80% LTV
30-year terms available
Qualify using 12 months of personal or business bank statements
No tax returns required
How Much Can You Pull Out?
It depends on the property value and the program you use.
Here's a quick example across programs:
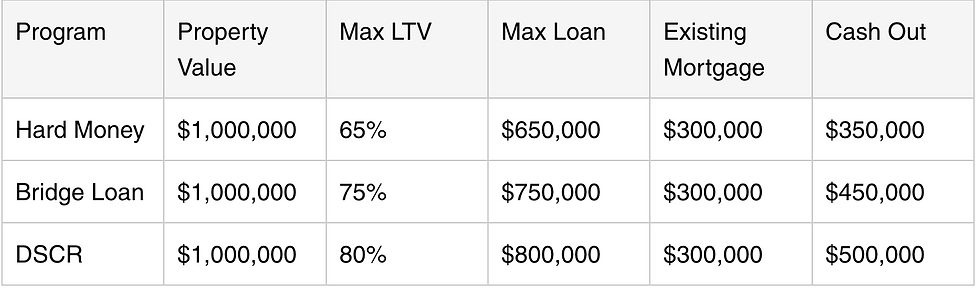
The higher the LTV — the more cash you can access. But higher LTV also means higher risk to the lender, which is reflected in the rate and qualification requirements.
What Property Types Qualify?
We fund cash-out refinances on:
Single family homes (1–4 units)
Condos and townhomes
Multi-family (5–10 units for most programs)
Mixed-use properties
Commercial properties (case by case)
Short-term rentals — Airbnb and VRBO eligible on DSCR programs
One important note on entity structure — we lend to LLCs, corporations, partnerships, and revocable trusts. You do not need to hold the property in your personal name to do a cash-out refinance through us.
Where This Comes Up Most
We see cash-out refinance requests across every market we lend in — a rehabbed rental in Sacramento County, a stabilized flip in Orange County, or a multi-unit hold in Los Angeles County. The underwriting approach stays the same regardless of where the property sits — it's about the asset and the equity, not the zip code.
Common Questions
How long do I need to own the property before I can cash out?
With private lending — there is no strict seasoning requirement on most programs. We lend based on current appraised value. If you bought a property, forced equity through renovation, and the value has increased — we can lend on that new value even if you've only owned it for a short time.
Conventional lenders typically require 6 to 12 months of seasoning. We don't.
Does the property need to be rented?
Not for hard money or bridge cash-out programs. We lend on the asset value regardless of occupancy. For DSCR cash-out — the property should be rented or rentable, since the qualification is based on rental income.
What if I have a hard money loan on the property already?
That's a very common scenario. We regularly do cash-out refinances that simultaneously pay off an existing hard money loan and put additional capital in your pocket. As long as the equity supports both — it works.
Can I do a cash-out on a property I own free and clear?
Yes. In fact, free and clear properties make the cleanest cash-out deals. No existing lien to pay off — the entire loan amount comes to you at closing.
The BRRRR Strategy and Cash-Out
If you're familiar with BRRRR — Buy, Rehab, Rent, Refinance, Repeat — cash-out refinancing is literally the engine that makes it work.
You buy a distressed property using hard money. You rehab it. You rent it. You refinance with a DSCR loan and pull your original capital back out. Then you do it again.
The cash-out refinance is step four. And it's what allows the strategy to be repeatable without constantly deploying new capital.
We fund every stage of that cycle:
Hard money for the acquisition and rehab
Bridge loans for the transition
DSCR cash-out for the permanent refinance
Bottom Line
Your equity is not just sitting there.
It's capital waiting to be redeployed.
Cash-out refinancing on investment properties is one of the most efficient ways to access that capital without selling the asset — and without the bank red tape that blocks most conventional applications.
If you have equity in a California investment property and want to put it to work — let's talk about what makes sense for your situation.
Ready to explore a cash-out refinance on your investment property?
South County Capital funds cash-out refinances on California investment properties — hard money, bridge, DSCR, and bank statement programs available.
California DRE License #01884316


